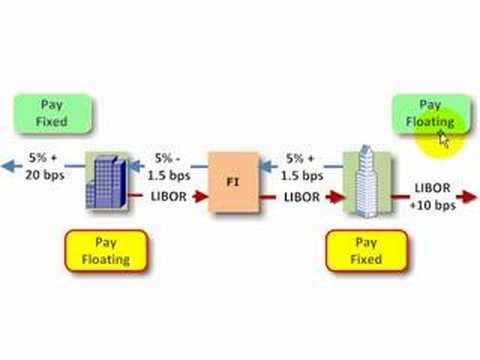
FRM: Interest rate swap
This illustrates how an interest rate swap can transform a floating-rate obligation into a fixed-rate obligation and vice-versa.
From: Bionic Turtle
Added: 18 years ago
Views: 171,273
18,018 ratings
Years
About 318 results
This illustrates how an interest rate swap can transform a floating-rate obligation into a fixed-rate obligation and vice-versa.
From: Bionic Turtle
Added: 18 years ago
Views: 171,273
Covariance is a measure of relationship (or co-movement) between two variables. Correlation is just the translation of covariance ...
From: Bionic Turtle
Added: 18 years ago
Views: 271,574
Lots of ways to estimate volatility. In this map, I parse out implied volatility (forward looking) and deterministic (constant) and focus ...
From: Bionic Turtle
Added: 18 years ago
Views: 51,537
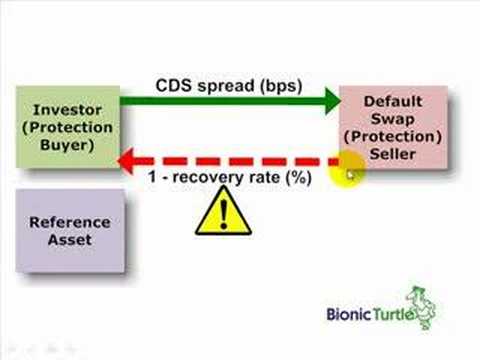
A CDS is a bilateral contract between two counterparties. The protection buyer is buying insurance: he/she pays premiums in ...
From: Bionic Turtle
Added: 18 years ago
Views: 101,996
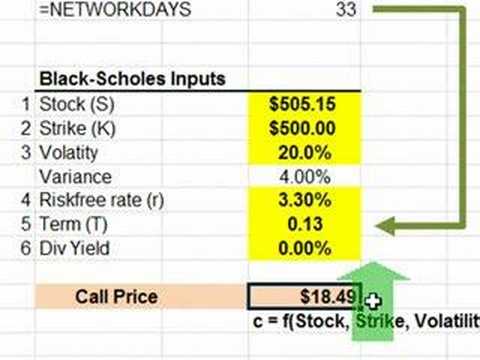
Using the market price for an option on Google's stock, I use Excel's GOAL SEEK function to estimate implied volatility. Implied ...
From: Bionic Turtle
Added: 18 years ago
Views: 108,631
A securitization is a structured finance with three ingredients: 1. Pooled credit-sensitive assets; 2. Transfer of credit risk; 3.
From: Bionic Turtle
Added: 18 years ago
Views: 47,918
An FRA is a contract that lets the buyer (who is long the rate) lock-in an interest (borrowing) rate. In this example, the FRA buyer ...
From: Bionic Turtle
Added: 18 years ago
Views: 115,701
A review of Michael Ong's unexpected loss (UL) for a single credit-asset. First, I briefly compare the various definitions of ...
From: Bionic Turtle
Added: 18 years ago
Views: 29,278
RAROC is a risk-adjusted performance measure (RAPM): risk-adjusted return divided by economic capital (i.e., the capital ...
From: Bionic Turtle
Added: 18 years ago
Views: 73,735
The binomial solves for the price of an option by creating a riskless portfolio. For more financial risk videos, visit our website!
From: Bionic Turtle
Added: 18 years ago
Views: 221,996
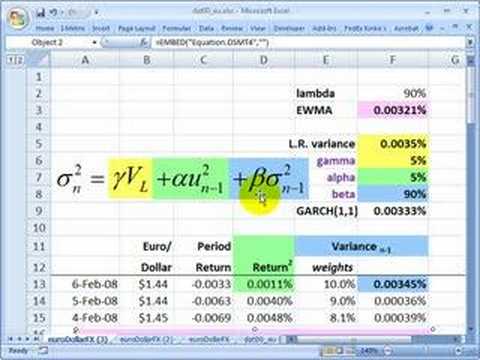
GARCH(1,1) estimates volatility in a similar way to EWMA (i.e., by conditioning on new information) EXCEPT it adds a term for ...
From: Bionic Turtle
Added: 18 years ago
Views: 195,044
A tricky learning objective in the FRM is "Discuss the effect maturity has on the price of a bond." Answer: Bond price increases with ...
From: Bionic Turtle
Added: 18 years ago
Views: 8,946
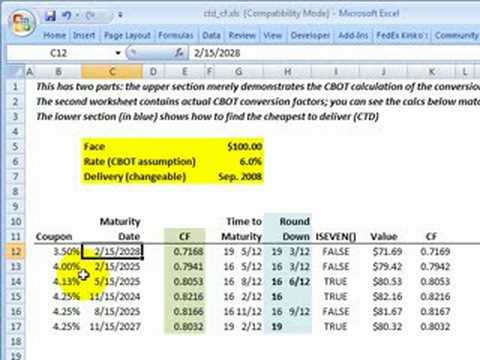
The short position in a US Treasury bond futures contract can select among many different eligible (maturity greater than 15 years) ...
From: Bionic Turtle
Added: 18 years ago
Views: 56,659
This is a brief review of the option Greeks. They are sensitivities: what is the change in option price with respect to [stock price ...
From: Bionic Turtle
Added: 18 years ago
Views: 67,550
The value of a European call must be equal to a replicating portfolio that has two positions: long a fractional (delta) share of stock ...
From: Bionic Turtle
Added: 18 years ago
Views: 85,689
A CLN is similar to a credit default swap (CDS): both transfer credit risk to investors. However, the CLN is FUNDED; the bond ...
From: Bionic Turtle
Added: 18 years ago
Views: 78,385
In the last screencast, we noted the role of the conversion factor (CF) is to make the short (in a Treasury bond futures contract) ...
From: Bionic Turtle
Added: 18 years ago
Views: 48,608
The basis is the difference between the spot and futures price. Basis risk attaches to all derivatives. For more financial risk videos, ...
From: Bionic Turtle
Added: 18 years ago
Views: 101,878
This video represents a very brief introduction to the "best fit" line through X:Y data. Subscribe to our channel for more financial ...
From: Bionic Turtle
Added: 18 years ago
Views: 386,439
P-STRIPS and C-STRIPS are popular because: 1. They can be combined or re-constructed into any required sequence of cash ...
From: Bionic Turtle
Added: 18 years ago
Views: 56,559